Understanding Medicaid Waiver Payments: Tax Rules for Caregivers
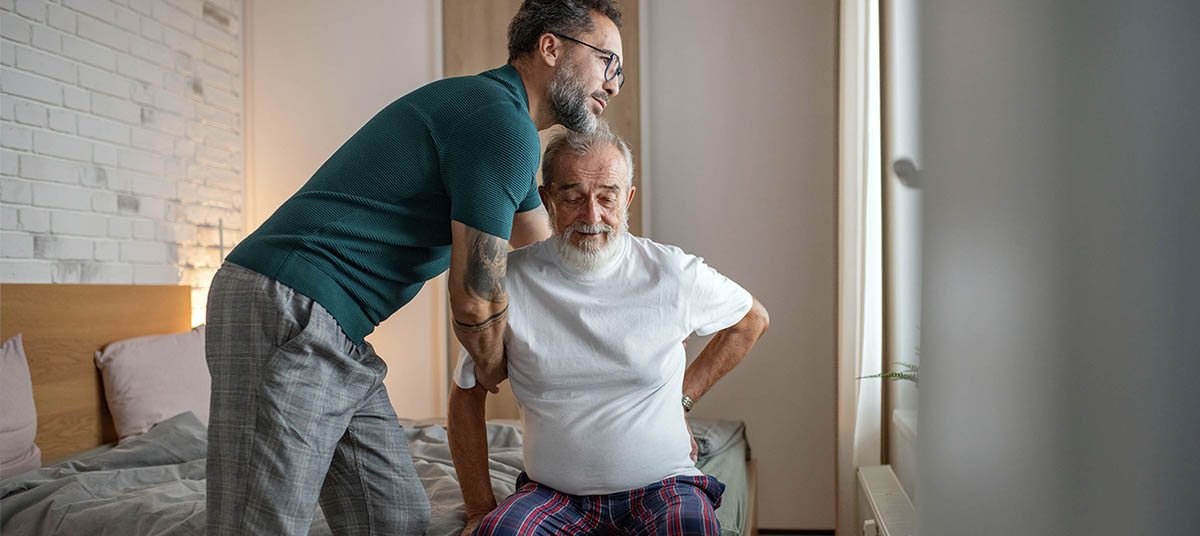
Medicaid waiver payments present a unique set of tax considerations, operating at the complex crossroads of healthcare, social support, and federal tax law. For many caregivers, these payments represent more than just compensation for daily caregiving duties. Crucially, they can also impact eligibility for valuable tax credits, including the Earned Income Tax Credit (EITC) and the Additional Child Tax Credit (ACTC).
Navigating these rules requires a clear understanding of what these payments represent, who is eligible to receive them, when they can be excluded from gross income, and how they may still count as earned income for tax credits. Because IRS guidance and key court rulings have evolved, caregivers must exercise careful planning when reporting these amounts on their tax returns.
Understanding Medicaid Waiver Payments
Medicaid waiver payments are distributed under state-approved programs designed to help individuals receive care in their own homes or community settings rather than in institutions. In practice, these funds are typically paid to family members or caregivers who provide “difficulty of care” services to individuals requiring daily assistance. These are formalized arrangements tied directly to state-approved programs, rather than informal family care agreements.
The policy objective behind these waivers is to reduce the reliance on institutional care, helping individuals with disabilities or chronic needs remain in comfortable, familiar environments. For caregivers, the payments help offset the significant time and financial commitment required to provide this level of care. From a public standpoint, these programs lower systemic costs while improving the recipient's quality of life and making home-based care financially viable for families.

Who Qualifies for the Tax Exclusion?
Qualification for favorable tax treatment depends on the specific state waiver program and the living arrangements of the caregiver and recipient. To qualify for the tax exclusion, a key requirement is that the caregiver and the care recipient must reside in the same home. This can be the home of either the caregiver or the recipient.
This shared-residency rule is absolute. If the caregiver and the recipient do not live together, the payments are fully taxable as regular income. This distinction is a frequent source of confusion, as many families mistakenly assume that all Medicaid waiver payments are automatically exempt from federal income tax.
When Are Medicaid Waiver Payments Excluded from Income?
Under IRS Notice 2014-7, qualified Medicaid waiver payments that meet the same-home requirement are excluded from gross income. This means eligible caregivers do not need to report these payments as taxable income on their federal tax returns.
However, the exclusion only applies when all statutory conditions, particularly the residency requirement, are met. If you do not live in the same home as the care recipient, the payments are treated as fully taxable income. While these qualifying payments may be excluded from gross income, tax law still allows them to be treated as earned income for specific tax credits—creating a valuable planning opportunity for eligible households.
Common Reporting Challenges and W-2 Codes
Reporting these payments can be complicated by how they are documented. Some taxpayers receive a Form W-2 showing their Medicaid waiver payments in Box 12 with code II. This code indicates that the payments are excluded from gross income under IRS Notice 2014-7. However, this exclusion does not mean the income is entirely ignored; caregivers may still choose to count it as earned income when calculating the EITC and ACTC.
In other cases, particularly in states utilizing self-certification systems, caregivers might not receive a Form W-2 at all due to administrative shifts. In the absence of a W-2, maintaining thorough records and documentation is essential for substantiating the payments when filing or amending tax returns to claim credits.
Treating Excluded Payments as Earned Income for Credits
Originally, the IRS maintained that because these payments were excluded from gross income, they could not be treated as earned income to qualify for the Earned Income Tax Credit (EITC) and the Additional Child Tax Credit (ACTC). This stance was challenged in a landmark Tax Court case involving Mary and Edward Feigh, who excluded Medicaid waiver payments received for caring for their disabled adult children in their home but still claimed them as earned income for credit purposes.
The Tax Court ruled in favor of the Feighs, and the IRS subsequently acquiesced to the decision. As a result, caregivers can now choose to treat these excluded payments as earned income to qualify for or increase their EITC and ACTC benefits.
Furthermore, the IRS rules provide a separate election for married couples filing jointly. If both spouses receive qualified Medicaid waiver payments, each spouse can independently decide whether to include their respective payments in earned income. This flexibility allows for precise tax planning to optimize the couple's overall tax credit calculation.
Amending Prior-Year Tax Returns
If you did not previously take advantage of these rules, you may be eligible to amend past tax returns to claim a refund, provided the tax year remains open under the refund statute of limitations. Generally, the federal statute of limitations allows taxpayers to amend a return within three years from the original filing deadline (or the date the return was filed, whichever is later) or two years from the date the tax was paid, whichever is later.
Amending a prior return to include qualified Medicaid waiver payments as earned income for the EITC and ACTC can generate substantial refunds for households that previously underclaimed or were denied these credits. For many family caregivers, separating the gross income exclusion from the earned-income treatment for credits can result in significant tax savings.
Navigating Your Caregiver Tax Benefits
Understanding the nuances of Medicaid waiver payments is essential for maximizing your available tax benefits while maintaining compliance. By carefully applying IRS Notice 2014-7 and the precedents set by the Feigh case, caregivers can protect their hard-earned income and secure vital tax credits.
At Ember Coaching & Financial Services, Chris Conway, CPA, and our team help family caregivers navigate these complex tax rules. Whether you need to file an accurate current-year return or review prior years for potential refund opportunities, we are here to help. Contact our offices in Breckenridge, CO, or Destin, FL, to schedule a consultation.
Want tax & accounting tips and insights?
Sign up for our newsletter.